
What Does a Solid Retirement Income Plan Actually Look Like in 2026?
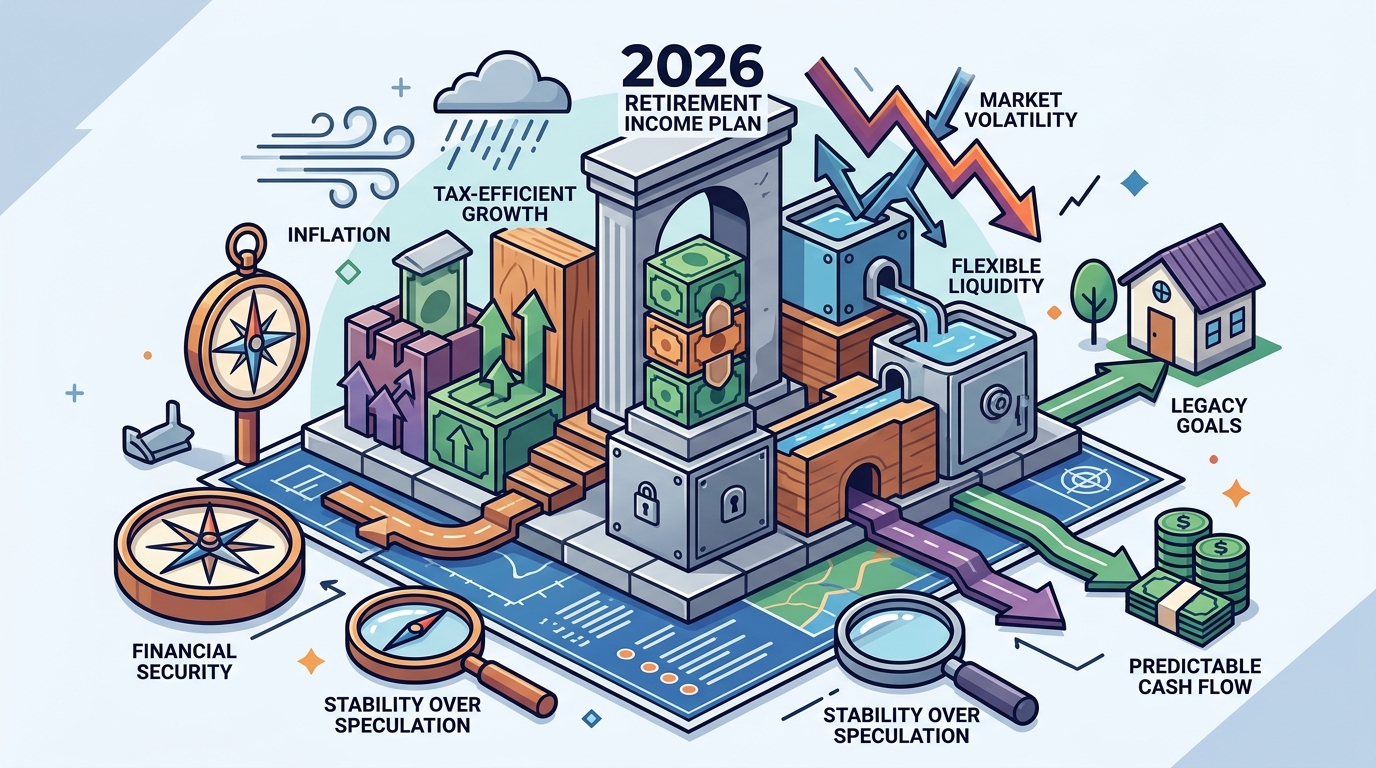
A solid retirement income plan in 2026 combines guaranteed income streams, tax-efficient growth, and flexible liquidity to protect against inflation and market volatility. It prioritizes stability over speculation, ensuring you have predictable cash flow to cover essential expenses while preserving wealth for legacy goals. American Gulf helps individuals build these plans using fixed annuities and tailored financial solutions.
The Foundation of Predictable Cash Flow
Retirement income planning begins with establishing a baseline of guaranteed payments. In an economy where interest rates fluctuate and market returns are uncertain, relying solely on variable investments can create dangerous gaps in your monthly budget. A fixed annuity is a contract with an insurance company that provides a guaranteed stream of income, typically for a specified period or for life. This product acts as a financial floor, ensuring that your essential expenses, such as housing, healthcare, and utilities, are covered regardless of how the stock market performs.
For many retirees, Social Security provides the first layer of income. However, this often falls short of pre-retirement earnings. By supplementing Social Security with a guaranteed income stream from a fixed annuity, you can close the gap between what you need and what you have. This approach reduces the risk of outliving your assets, a primary fear for those planning their 60s and 70s. The predictability of these payments allows for better budgeting and peace of mind, knowing that a portion of your income is immune to economic shocks.
Tax-Deferred Growth and Inflation Protection
While guaranteed income is crucial, the growth of your capital during the accumulation phase is equally important. A multi-year guaranteed annuity (MYGA) is a single premium deferred annuity designed for long-term retirement savings, offering tax-deferred growth. This means you do not pay taxes on the interest earned until you withdraw the funds, allowing your money to compound more effectively over time. In today's economy, where inflation erodes purchasing power, tax-deferred growth helps maintain the real value of your savings.
Fixed annuities also offer protection against market volatility. Unlike variable investments, the principal in a fixed annuity is guaranteed to grow at a predetermined rate for the contract term. This stability is vital for risk-averse investors who cannot afford significant drawdowns. By locking in rates during periods of higher interest, you can secure a predictable growth trajectory. This strategy is particularly useful for those who are close to retirement and need to protect their nest egg from sudden market corrections.
Flexibility and Liquidity Considerations
A robust retirement plan must balance security with flexibility. While fixed annuities provide guaranteed income, they may have surrender charges if you withdraw funds early. Therefore, it is important to structure your portfolio so that you maintain sufficient liquid assets for short-term needs. This might include a cash reserve or a mix of different annuity terms. By diversifying your income sources, you can access funds when needed without incurring heavy penalties or taxes.
Consider the concept of annuitization, which is the process of converting the premiums and interest of a deferred annuity into a stream of income. You can choose to annuitize a portion of your portfolio while keeping the rest in other investments. This hybrid approach allows you to benefit from the safety of guaranteed income while retaining some exposure to market growth. It is a strategic way to manage risk and maximize returns over your retirement horizon. according to The development of
Legacy Planning and Estate Considerations
Retirement planning is not just about your own needs; it also involves leaving a legacy for your loved ones. Many fixed annuities offer death benefits that pass the remaining value to your beneficiaries. This ensures that your family is financially supported even after your passing. By integrating legacy planning into your income strategy, you can provide for your heirs while securing your own retirement. This dual purpose makes annuities a versatile tool in comprehensive financial planning.
Additionally, preneed insurance can be part of a broader legacy plan. Preneed insurance is a policy that covers funeral expenses, locking in today's prices and easing the financial burden on your family. By addressing these costs in advance, you reduce the stress and expense for your loved ones during a difficult time. This holistic approach to planning ensures that all aspects of your financial future are covered, from your own income to your family's peace of mind.
Key Takeaways
- A solid retirement plan combines guaranteed income, tax-deferred growth, and flexible liquidity.
- Fixed annuities provide a stable income floor, protecting essential expenses from market volatility.
- Multi-year guaranteed annuities (MYGAs) offer tax-deferred growth, helping to combat inflation.
- Diversifying income sources allows for better cash flow management and reduced risk.
- Legacy planning ensures that your assets support your beneficiaries after your passing.
- Preneed insurance locks in funeral costs, reducing financial strain on your family.
Frequently Asked Questions
What is a fixed annuity?
A fixed annuity is an insurance contract that provides a guaranteed stream of income, typically for a specified period or for life, with a fixed interest rate independent of market fluctuations.
How do multi-year guaranteed annuities (MYGAs) work?
MYGAs are single premium deferred annuities that offer tax-deferred growth at a guaranteed rate for a set term, such as 5, 6, or 7 years, before you can access the funds.
Are annuities safe investments?
Yes, fixed annuities are generally considered safe because the principal is guaranteed to grow at a fixed rate, and they are backed by the insurance company's claims-paying ability.
Can I withdraw money from an annuity early?
You can usually withdraw money early, but you may be subject to surrender charges and taxes, especially if you are under age 59 .
How does a fixed annuity help with inflation?
While fixed rates do not adjust for inflation, tax-deferred growth helps preserve the real value of your money, and you can combine annuities with other investments to manage inflation risk.
What is the difference between a fixed and variable annuity?
A fixed annuity offers a guaranteed rate of return, while a variable annuity allows you to invest in subaccounts with market-linked returns, which can fluctuate. according to The development of
How can I start planning my retirement income?
You can start by consulting with a financial advisor to assess your needs and explore options like fixed annuities and preneed insurance to build a comprehensive plan.
Start Building Your Plan Today
Creating a solid retirement income plan requires careful consideration of your goals, risk tolerance, and financial situation. By combining guaranteed income streams with tax-efficient growth and legacy planning, you can secure a stable and comfortable retirement. American Gulf offers expert guidance to help you navigate these options and build a plan that fits your unique needs. To explore how a fixed annuity could fit your retirement strategy, for a personalized consultation.