
Fixed annuities provide steady retirement income by converting a lump sum into guaranteed, predictable payments. This mechanism shields your principal from market volatility while ensuring a consistent cash flow. American Gulf offers these solutions to help you secure a reliable financial foundation for your later years.
The Mechanics of Guaranteed Payouts
Fixed annuities operate on a straightforward principle: you invest a sum of money, and the insurance company guarantees a specific return. This structure eliminates the uncertainty associated with variable investments. The income stream is calculated based on the contract terms, ensuring you know exactly what to expect each month.
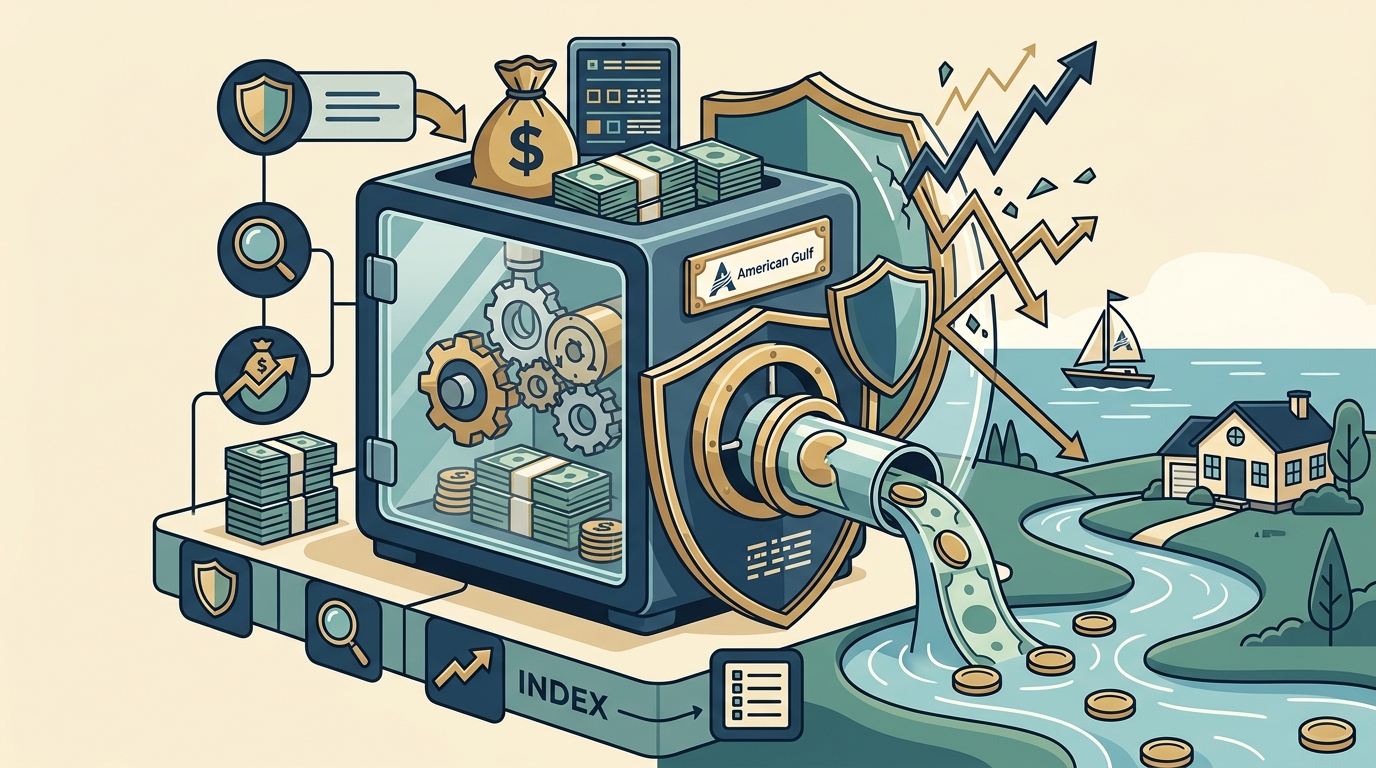
When you purchase a fixed annuity, you enter a contract with an insurance provider. The provider uses the premiums you pay to invest in a portfolio of fixed-income securities. These investments generate interest, which is then credited to your account. Because the underlying assets are stable, the income you receive is also stable.
This predictability is crucial for retirees who rely on their savings for daily expenses. Unlike stocks or bonds, which can fluctuate in value, a fixed annuity provides a steady drip of income. This allows you to budget with confidence, knowing that your essential costs will be covered regardless of economic conditions.
Tax-Deferred Growth and Compounding
One of the most powerful features of a fixed annuity is tax-deferred growth. This means you do not pay taxes on the interest earned until you withdraw the money. This delay in taxation allows your money to compound more effectively over time.
American Gulf emphasizes this tax advantage as a key benefit for long-term planning. When you are ready to retire, you can choose to withdraw funds or convert the account into a stream of income. The tax-deferred nature of the account helps maximize the amount of money available for your retirement years.
Protection Against Market Volatility
Market volatility can erode retirement savings, especially during economic downturns. Fixed annuities provide a buffer against these fluctuations by guaranteeing a minimum return. Your principal is protected, and your income stream remains consistent even when the broader market is unstable.
This protection is vital for retirees who cannot afford to take on significant risk. If you withdraw money from a volatile portfolio during a market crash, you may lock in losses and deplete your savings faster. A fixed annuity avoids this risk by decoupling your income from market performance.
By including a fixed annuity in your retirement portfolio, you create a stable core of income. This allows you to invest the rest of your assets in higher-growth opportunities without jeopardizing your essential expenses. This balanced approach helps ensure that your retirement lasts as long as you do.
Choosing the Right Payout Option
When you are ready to start receiving income, you can choose from several payout options. The most common is a lifetime income stream, which pays you a fixed amount every month for the rest of your life. This option provides maximum security, as you will never outlive your money.
Another option is a term certain payout, which pays you for a specific number of years, such as 10 or 20 years. If you pass away before the term ends, the remaining payments go to your beneficiary. This option can be useful if you want to leave an inheritance while still securing your own income.
It is important to consider your life expectancy and financial goals when choosing a payout option. A lifetime income stream is ideal for those who want absolute security, while a term certain payout may be better for those who want to leave assets to their heirs. Consulting with a financial advisor can help you determine the best option for your situation.
Integrating Annuities into Your Retirement Plan
Fixed annuities are not a one-size-fits-all solution. They should be part of a broader retirement strategy that includes other assets like stocks, bonds, and cash. By diversifying your portfolio, you can balance the stability of annuities with the growth potential of other investments.
American Gulf recommends that clients work with a financial advisor to determine the right mix of assets for their retirement. This personalized approach ensures that your income needs are met while preserving the growth potential of your portfolio. The goal is to create a sustainable income stream that supports your lifestyle throughout retirement.
As you approach retirement, it is important to review your annuity contract and understand the terms. This includes the surrender period, which is the time you must wait before you can withdraw your money without penalties. By understanding these details, you can make informed decisions about your financial future.
Key Takeaways
- Fixed annuities convert a lump sum into guaranteed, predictable monthly payments.
- Tax-deferred growth allows your money to compound more effectively over time.
- Fixed annuities protect your principal and income stream from market volatility.
- You can choose between lifetime income and term certain payout options.
- Fixed annuities should be part of a diversified retirement portfolio.
- Consulting with a financial advisor helps you choose the right payout option.
- Understanding contract terms, such as surrender periods, is crucial for planning.
Frequently Asked Questions
What is a fixed annuity?
A fixed annuity is an insurance contract that provides a guaranteed rate of return on your investment. It is designed to provide a steady stream of income during retirement.
How does a fixed annuity protect my money?
A fixed annuity protects your money by guaranteeing a minimum return and shielding your principal from market fluctuations. This ensures that your income stream remains stable.
Are fixed annuities tax-advantaged?
Yes, fixed annuities offer tax-deferred growth. You do not pay taxes on the interest earned until you withdraw the money, which allows your savings to compound more effectively.
What are the different payout options for a fixed annuity?
Common payout options include lifetime income, which pays you for the rest of your life, and term certain, which pays you for a specific number of years. You can also choose a lump sum withdrawal.
How long is the surrender period for a fixed annuity?
The surrender period is typically 5 to 10 years. During this time, you may face penalties if you withdraw your money. After the surrender period, you can usually withdraw your funds without penalties.
Can I use a fixed annuity to leave an inheritance?
Yes, you can choose a term certain payout option, which pays your beneficiary any remaining payments if you pass away before the term ends. This allows you to secure your own income while leaving assets to your heirs.
How do I choose the right fixed annuity for my retirement?
Consider your income needs, life expectancy, and financial goals when choosing a fixed annuity. Consulting with a financial advisor can help you determine the best option for your situation.
Secure Your Retirement with American Gulf
Planning for retirement requires careful consideration of your income needs and risk tolerance. Fixed annuities offer a reliable way to secure a steady income stream while protecting your principal from market volatility. By understanding the mechanics of fixed annuities and choosing the right payout option, you can create a sustainable financial foundation for your later years.
American Gulf is committed to helping you achieve financial stability and peace of mind. Our team of experts can guide you through the process of selecting the right fixed annuity for your retirement goals. To learn more about how fixed annuities can fit into your retirement plan, today.