
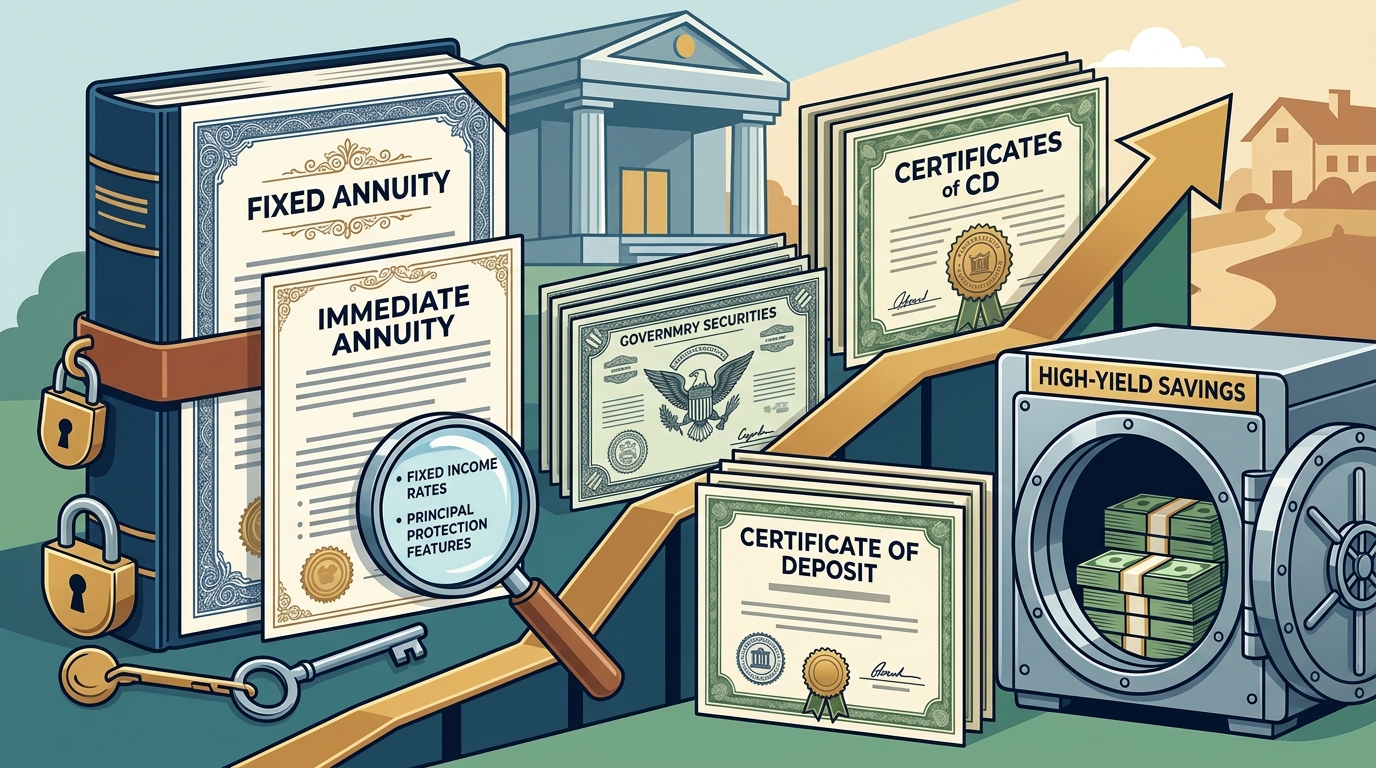
Retirees seeking guaranteed returns should prioritize fixed annuities, Treasury securities, and certificates of deposit. These instruments offer principal protection and predictable income. This guide details how to build a stable portfolio using these low-risk assets. It also covers immediate annuities and high-yield savings accounts. American Gulf provides expert guidance on these retirement solutions.
Fixed Annuities
A fixed annuity is an insurance contract that provides a guaranteed interest rate independent of market fluctuations. These products serve as a cornerstone for conservative investors. They protect your principal while allowing for tax-deferred growth. The interest compounds over a set term, ensuring predictable outcomes.
Multi-Year Guaranteed Annuities
Multi-Year Guaranteed Annuities (MYGAs) are single premium deferred annuities. They are suitable for long-term retirement savings. You can hold them in IRAs or as taxable alternatives to CDs. The growth is based on a predetermined compounded rate. This structure shields your funds from market volatility.
Tax-Deferred Growth
Earnings in a fixed annuity grow tax-deferred. You pay taxes only when you withdraw the interest. This allows your money to compound more efficiently. In taxable accounts, annual taxes reduce the amount available for reinvestment. Fixed annuities avoid this drag, enhancing long-term returns.
Treasury Securities
Treasury securities are debt instruments issued by the U.S. government. They are considered the safest investment in the world. Backed by the full faith and credit of the nation, they carry no credit risk. Investors can choose from bills, notes, and bonds based on their time horizon.
Types of Treasuries
Treasury bills mature in one year or less. Treasury notes have maturities between two and ten years. Treasury bonds last more than ten years. Each type offers a fixed interest rate. The price fluctuates with interest rate changes, but holding to maturity guarantees the face value.
Income and Safety
Treasury securities provide regular interest payments. This creates a reliable income stream for retirees. The principal is protected if held to maturity. They are highly liquid and can be sold on the secondary market. This flexibility makes them a vital part of a balanced portfolio.
Certificates of Deposit
A certificate of deposit (CD) is a bank product that offers a fixed interest rate for a specific term. CDs are insured by the FDIC up to applicable limits. This provides a high level of security for depositors. They are simple to understand and easy to access.
Term and Liquidity
CDs come in various terms, from three months to ten years. Longer terms typically offer higher interest rates. However, early withdrawal may incur penalties. Retirees should match CD terms with their cash flow needs. Laddering CDs can provide both yield and liquidity.
Comparison with Annuities
Strategic Tips
Building a guaranteed return portfolio requires careful planning. Diversification across asset classes reduces risk. Retirees should align their investments with their income needs. Here are key strategies to consider.
Diversify Your Holdings
Do not rely on a single instrument. Combine fixed annuities, Treasuries, and CDs. This spreads risk and smooths returns. Different assets react differently to economic changes. A diversified portfolio provides stability and flexibility.
Consider Inflation Protection
Review Your Portfolio Regularly
Market conditions and personal needs change over time. Review your portfolio annually. Adjust allocations as needed. Ensure your income stream matches your expenses. Regular reviews help maintain alignment with your goals.
Immediate Annuities
An immediate annuity is a contract that begins paying income shortly after purchase. It converts a lump sum into a steady stream of payments. This provides guaranteed lifetime income. It protects against outliving your savings.
Income for Life
Immediate annuities offer the option for lifetime payments. This eliminates longevity risk. The insurer assumes the risk of you living longer than expected. Payments are based on actuarial tables. This ensures a reliable income floor for retirement.
Choosing the Right Option
Consider your health and family history. These factors influence the value of lifetime income. Compare quotes from different insurers. Look for strong financial ratings. American Gulf offers expert guidance on selecting the right annuity for your needs.
High-Yield Savings
High-yield savings accounts offer competitive interest rates with full liquidity. They are FDIC insured, providing maximum safety. These accounts are ideal for emergency funds. They allow you to access your money without penalties.
Liquidity and Access
Role in Retirement
High-yield savings serve as a cash reserve. They cover unexpected expenses without tapping into long-term investments. This preserves your guaranteed return assets. Maintain a buffer of six to twelve months of expenses. This provides peace of mind and financial resilience.
Comparison of Guaranteed Return Options
| Instrument | Principal Protection | Tax Treatment | Liquidity | Income Type |
|---|---|---|---|---|
| Fixed Annuity | Guaranteed by insurer | Tax-deferred | Low (surrender charges) | Deferred or Immediate |
| Treasury Securities | Guaranteed by U.S. Gov | Federal tax, state exempt | High (secondary market) | Periodic Interest |
| Certificate of Deposit | FDIC Insured | Taxable annually | Low (early withdrawal penalty) | Fixed Interest |
| High-Yield Savings | FDIC Insured | Taxable annually | High | Variable Interest |
Key Takeaways
- Fixed annuities offer tax-deferred growth and guaranteed interest rates.
- Treasury securities provide the highest level of safety and liquidity.
- Certificates of deposit are FDIC insured and offer fixed terms.
- Immediate annuities convert lump sums into guaranteed lifetime income.
- High-yield savings accounts provide liquidity and emergency fund protection.
- Diversification across these instruments reduces overall portfolio risk.
- Regular portfolio reviews ensure alignment with changing needs.
- Consult with a licensed agent to select the right products for your plan.
Frequently Asked Questions
Are fixed annuities FDIC insured?
No, fixed annuities are not FDIC insured. They are backed by the financial strength of the insurance company. Guarantees are based on the insurer's claims-paying ability.
What is the difference between a fixed and variable annuity?
A fixed annuity offers a guaranteed interest rate. A variable annuity invests in subaccounts, with returns fluctuating based on market performance. Fixed annuities carry no market risk.
How do Treasury securities protect against inflation?
Standard Treasuries do not adjust for inflation. Treasury Inflation-Protected Securities (TIPS) adjust their principal based on inflation. This helps preserve purchasing power.
Can I withdraw from a CD early?
Yes, but you may incur a penalty. The penalty is typically a few months of interest. This reduces your overall return. Plan your withdrawals carefully to avoid penalties.
What is an immediate annuity?
An immediate annuity begins paying income shortly after purchase. It converts a lump sum into a steady stream of payments. This provides guaranteed lifetime income.
How much should I keep in high-yield savings?
Experts recommend keeping six to twelve months of expenses. This provides a buffer for unexpected costs. It preserves your long-term investments.
How do I choose the right fixed annuity?
Consider the term, interest rate, and insurer's financial strength. Look for tax-deferred growth and guaranteed minimum rates. Consult with a licensed agent for personalized advice.