
Retirement planning requires more than just saving; it demands strategic allocation of assets to withstand market volatility and inflation. According to recent industry analyses, over 60% of Americans rely heavily on Social Security, which often replaces less than half of their pre-retirement income. This gap necessitates robust alternative strategies, such as utilizing fixed annuities to bridge the shortfall. Understanding the distinct mechanics of these financial instruments is the first step toward securing a prosperous future.
What Are Fixed Annuities?
A fixed annuity is a contract between an individual and an insurance company where the insurer guarantees a specific interest rate for a set period. This product is designed for long-term accumulation of money, providing a predictable growth trajectory that is immune to stock market fluctuations. Unlike variable products, the principal is protected, and the interest rate is locked in, offering peace of mind for conservative investors. (ESG 8211 American Gulf)
At American Gulf, we specialize in these secure retirement solutions. Our approach focuses on straightforward, easy-to-choose options that eliminate complexity. We believe annuities should give you confidence, not confusion. By partnering with Gulf Guaranty Life Insurance Company, we ensure that your financial stability is backed by a legacy of trust and reliability.
Fixed annuities are particularly effective for individuals seeking to avoid the stress of market timing. The guaranteed growth allows you to plan your retirement income with precision. This predictability is crucial for those who prioritize financial security over speculative gains.
Traditional Savings Mechanics
Traditional savings accounts, such as high-yield savings accounts (HYSA) or certificates of deposit (CDs), offer liquidity and principal protection. However, they are subject to interest rate risk. When the Federal Reserve adjusts rates, the yield on these accounts fluctuates, often failing to outpace inflation over long periods.
A savings account is a deposit held at a bank or credit union that earns interest and allows for easy access to funds. While FDIC insurance protects these deposits up to $250,000, the returns are typically modest. In contrast, a certificate of deposit is a time-bound deposit that offers a fixed interest rate in exchange for locking away funds for a specific term.
The primary limitation of traditional savings is the lack of tax efficiency. Interest earned in these accounts is taxed as ordinary income in the year it is received. This immediate tax liability can erode compounding benefits over decades. For high-net-worth individuals, this can result in a significant drag on overall portfolio performance.
Key Differences in Growth and Risk
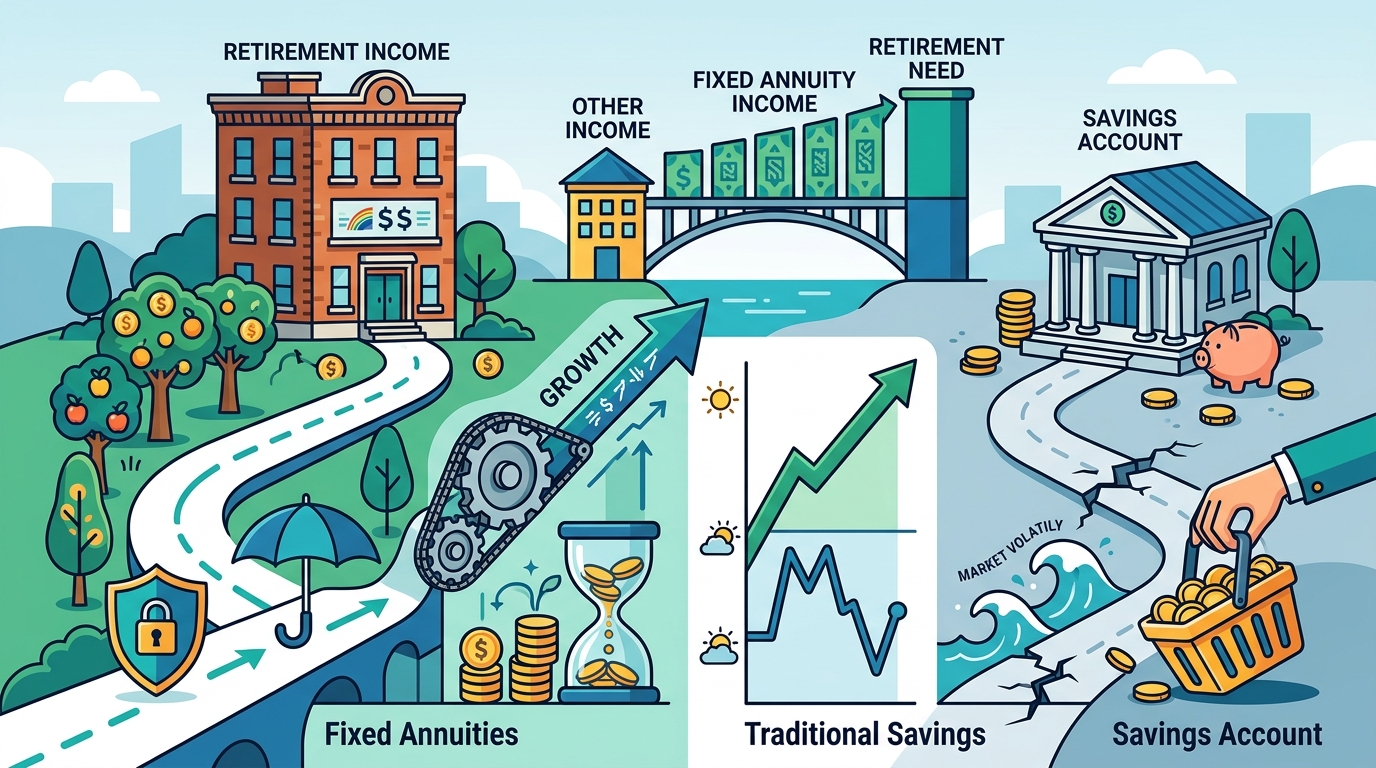
The most significant divergence between fixed annuities and traditional savings lies in the growth potential and risk profile. Fixed annuities often offer higher guaranteed interest rates than traditional savings accounts, especially in environments where bank rates are low. This is because insurance companies invest the premiums in a diversified portfolio of bonds and other fixed-income assets.
Risk in traditional savings is primarily inflation risk. If inflation rises above the interest rate earned, the purchasing power of the savings decreases. In fixed annuities, the risk is interest rate risk if rates rise after the contract is issued, locking you into a lower rate. However, multi-year guaranteed annuities (MYGAs) mitigate this by locking in rates for 3 to 10 years.
Data shows that over a 10-year period, fixed annuities have historically outperformed traditional savings accounts in terms of total return, particularly when interest rate environments are volatile. This outperformance is due to the ability of insurance companies to lock in long-term yields that banks cannot match.
Tax Implications and Deferral
Tax efficiency is a major advantage of fixed annuities. Earnings in a fixed annuity grow tax-deferred until withdrawal. This means you do not pay taxes on the interest each year, allowing your money to compound faster. In traditional savings, you pay taxes annually, which reduces the amount of capital available to grow.
Annuity withdrawals are subject to income tax, and withdrawals prior to age 59½ may also be subject to an IRS penalty. This early withdrawal penalty is a critical consideration for younger investors. However, for those nearing retirement, the tax deferral benefit is substantial.
If you annuitize a non-qualified annuity, a portion of your payment will be considered a return of premium and will not be subject to ordinary income tax. The amount that is taxable will be determined at the time you elect to annuitize the policy. This exclusion ratio can significantly reduce the tax burden on retirement income.
Liquidity and Access to Funds
Liquidity refers to how quickly and easily an asset can be converted into cash without significant loss of value. Traditional savings accounts offer high liquidity, allowing you to withdraw funds at any time without penalty. Fixed annuities, however, have surrender periods during which early withdrawals incur fees.
Surrender and withdrawal fees may apply on early withdrawals. These fees typically decrease over time, often reaching zero after 5 to 10 years. This structure encourages long-term commitment, which aligns with the goal of retirement planning. It prevents investors from making impulsive decisions that could derail their financial goals.
For those who need immediate access to cash, traditional savings remain the superior choice. However, for retirement funds that do not need to be accessed for decades, the liquidity trade-off is worth the higher guaranteed returns. American Gulf provides tools to help you estimate your retirement income and see how an annuity could fit your plan.
Comparison Summary
The following table summarizes the key differences between fixed annuities and traditional savings accounts.
| Feature | Fixed Annuities | Traditional Savings (HYSA/CD) |
|---|---|---|
| Growth Potential | Guaranteed fixed interest rate, often higher than banks | Variable rate, subject to market changes |
| Tax Treatment | Tax-deferred growth | Taxed annually as ordinary income |
| Liquidity | Surrender charges apply in early years | High liquidity, no penalties |
| Risk Profile | Low risk, backed by insurance company strength | Very low risk, FDIC insured |
| Best For | Long-term retirement planning | Short-term goals and emergency funds |
Key Takeaways
- Legacy of Trust: American Gulf is backed by Gulf Guaranty Life Insurance Company, founded in 1970, with over 50 years of expertise in financial services.
- Tax Efficiency: Fixed annuities offer tax-deferred growth, allowing compounding to work more effectively than in taxable savings accounts.
- Guaranteed Growth: Unlike variable investments, fixed annuities provide a locked-in interest rate, protecting against market downturns.
- Expansion: American Gulf has expanded across the South, including Tennessee, Louisiana, Arkansas, and Alabama, with licenses in Texas, Kentucky, and more.
- Rebranding: In 2025, Gulf Guaranty was acquired by Acturion and rebranded as American Gulf, focusing on secure retirement solutions.
- Digital Process: Our streamlined digital flow replaces paperwork, allowing you to e-sign, track, and fund without delays.
- Financial Strength: We maintain high financial strength ratings, ensuring our ability to meet long-term obligations and pay claims.
Frequently Asked Questions
What is a fixed annuity?
A fixed annuity is an insurance contract that guarantees a specific interest rate for a set period, providing predictable growth and principal protection.
Are fixed annuities FDIC insured?
No, fixed annuities are not FDIC or NCUA insured. They are backed by the financial strength and claims-paying ability of the issuing insurance company, such as Gulf Guaranty.
Can I withdraw money from a fixed annuity early?
Yes, but surrender and withdrawal fees may apply on early withdrawals. These fees typically decrease over the surrender period, which can last from 3 to 10 years.
How do fixed annuities compare to CDs?
Fixed annuities often offer higher guaranteed interest rates than CDs and provide tax-deferred growth, whereas CDs offer FDIC insurance and immediate liquidity.
What is the tax penalty for early withdrawal?
Withdrawals prior to age 59½ may be subject to an IRS penalty of 10% on the earnings portion of the withdrawal, in addition to ordinary income tax.
How can I estimate my retirement income?
You can use our online tool to run a quick scenario and see how an annuity could fit your plan based on your state and financial goals.
Is American Gulf available in my state?
American Gulf offers products in many states across the South, including Texas, Florida, Georgia, and Illinois. Please visit our products page for a current list of licensed states.
Contact Us
Ready to secure your financial future? Our experts take the time to assess your situation and recommend tailored insurance and financial solutions. Contact us today to learn more about our fixed annuities and how they can help you achieve your retirement goals.
You can reach our customer hotline at (844) USA-GULF or visit our contact page to send a message. We are here to help you navigate your options with clarity and confidence.