
Retirement planning requires more than just saving money; it requires protecting that money from market volatility and inflation. According to the U.S. Department of Labor, nearly 40% of Americans have less than $25,000 in retirement savings, highlighting the critical need for secure growth vehicles. Traditional savings accounts offer liquidity but often fail to outpace inflation. In contrast, fixed annuities provide guaranteed interest rates and tax-deferred growth, making them a powerful tool for long-term financial stability. Understanding the distinct advantages of each is essential for building a resilient retirement portfolio.
Understanding Fixed Annuities
A fixed annuity is a contract between an individual and an insurance company. The insurer promises to pay the policyholder a guaranteed rate of interest for a specified period. This structure provides predictability in an unpredictable financial landscape. At American Gulf, we specialize in helping clients navigate these products to ensure their retirement income is secure. Our approach focuses on clarity and simplicity, ensuring you understand exactly how your money grows.
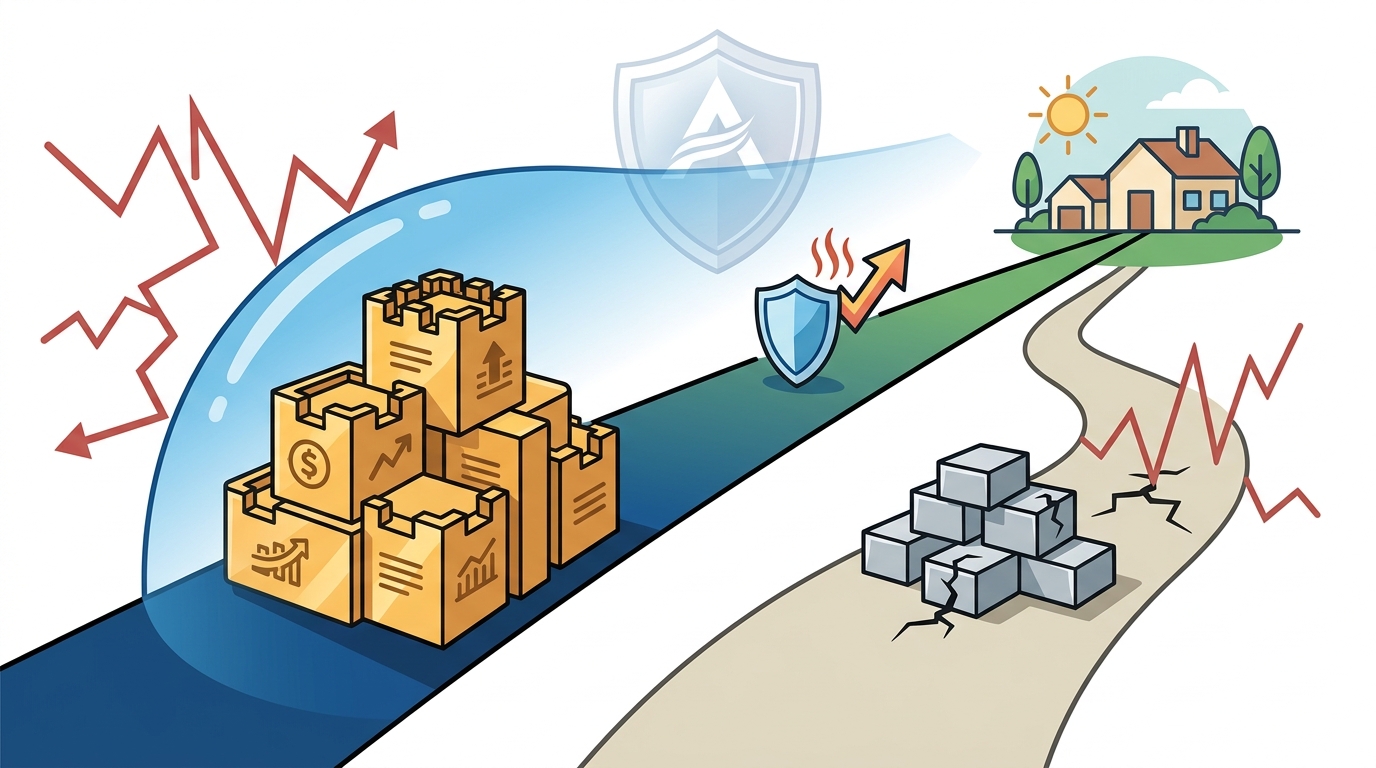
Fixed annuities are designed for long-term accumulation of money. They offer a safe harbor for capital that cannot afford to lose value. Unlike stocks or mutual funds, the principal is protected from market downturns. This makes them ideal for conservative investors who prioritize stability over speculative gains. The guaranteed interest rate allows for precise financial planning, as you know exactly how much your investment will be worth at maturity.
We offer personalized guidance to help you assess your specific needs. Our experts take the time to understand your objectives and recommend tailored solutions. This ensures that the annuity fits seamlessly into your broader financial plan. For more information on our products, visit our products page.
Traditional Savings Limitations
Traditional savings accounts, such as high-yield savings accounts (HYSAs) and certificates of deposit (CDs), are familiar tools for many. They offer FDIC insurance, which protects deposits up to $250,000 per depositor, per insured bank. This safety net is a significant advantage for short-term goals and emergency funds. However, these accounts often struggle to keep pace with inflation over the long term.
Inflation erodes purchasing power over time. If the interest rate on your savings account is lower than the inflation rate, your real return is negative. This means you are effectively losing money in terms of what it can buy. Fixed annuities, by contrast, often offer competitive interest rates that are locked in for the duration of the contract. This protection against inflation is crucial for retirement planning.
Additionally, traditional savings accounts are subject to immediate taxation on interest earned. This can reduce the net return, especially for individuals in higher tax brackets. Annuities offer a tax-advantaged alternative that can help maximize growth. To learn more about our financial strength and reliability, check out our about us section.
Key Differences in Growth and Risk
The primary difference between fixed annuities and traditional savings lies in growth potential and risk profile. Fixed annuities typically offer higher interest rates than traditional savings accounts. This is because the insurance company assumes the investment risk. In return, the policyholder receives a guaranteed return. This trade-off is beneficial for those who want to avoid market volatility.
Traditional savings accounts offer lower returns but greater flexibility. You can withdraw funds at any time without penalty. This liquidity is essential for unexpected expenses. However, the lower returns may not be sufficient for long-term goals like retirement. Fixed annuities require a longer commitment, but the guaranteed growth can significantly enhance your retirement income.
Here is a comparison of the key features:
| Feature | Fixed Annuities | Traditional Savings |
|---|---|---|
| Interest Rate | Guaranteed, often higher | Variable, often lower |
| Tax Treatment | Tax-deferred growth | Taxable annually |
| Liquidity | Limited, surrender charges may apply | High, immediate access |
| Insurance | Guaranteed by insurer | FDIC insured |
| Best For | Long-term retirement planning | Emergency funds, short-term goals |
Tax Implications and Deferral
Tax efficiency is a major advantage of fixed annuities. Interest earned in a traditional savings account is taxed as ordinary income in the year it is earned. This can significantly reduce your net return, especially if you are in a high tax bracket. Fixed annuities allow for tax-deferred growth. This means you do not pay taxes on the interest until you withdraw the funds.
Tax deferral allows your money to compound faster. You are effectively earning interest on your interest without the drag of annual taxes. This can lead to a substantially larger nest egg over time. However, it is important to note that withdrawals are subject to income tax. Withdrawals prior to age 59½ may also be subject to an IRS penalty of 10%. This makes fixed annuities best suited for long-term retirement planning.
Understanding these tax implications is crucial for making informed decisions. Our team at American Gulf is here to help you navigate these complexities. We provide clear, straightforward guidance to ensure you make the best choice for your financial future. For more details on our services, visit our contact page.
Liquidity and Access to Funds
Liquidity refers to how easily you can access your money without losing value. Traditional savings accounts offer high liquidity. You can withdraw funds at any time without penalty. This is ideal for emergency funds or short-term goals. Fixed annuities, on the other hand, have limited liquidity. They are designed for long-term growth, and early withdrawals may incur surrender charges.
Surrender charges are fees imposed by the insurance company if you withdraw funds before the end of the surrender period. This period typically lasts several years. The charges usually decrease over time, eventually reaching zero. This structure encourages long-term commitment and helps the insurance company manage its investments. It also ensures that the guaranteed interest rate remains stable for all policyholders.
It is important to balance liquidity needs with growth goals. Using a combination of both fixed annuities and traditional savings can provide the best of both worlds. Keep an emergency fund in a high-yield savings account and invest the rest in a fixed annuity for retirement. This strategy ensures you have access to cash when needed while maximizing long-term growth. To see how an annuity could fit your plan, use our retirement income estimator.
Choosing the Right Path
Choosing between fixed annuities and traditional savings depends on your financial goals, risk tolerance, and time horizon. If you need immediate access to your funds or are saving for a short-term goal, traditional savings may be more appropriate. However, if you are planning for retirement and want guaranteed growth, fixed annuities are likely the better choice.
Consider your overall financial picture. Do you have an emergency fund? Are you maximizing other tax-advantaged accounts like 401(k)s or IRAs? Fixed annuities can complement these accounts by providing a stable, guaranteed income stream in retirement. They can also help diversify your portfolio, reducing overall risk. Our experts at American Gulf can help you evaluate your options and create a personalized plan. Learn more about our ESG initiatives and commitment to integrity.
Remember, there is no one-size-fits-all solution. The best choice depends on your unique circumstances. Take the time to understand the pros and cons of each option. Consult with a financial advisor to ensure your decision aligns with your long-term goals. We are here to help you every step of the way.
Key Takeaways
- Fixed annuities offer guaranteed interest rates and tax-deferred growth, making them ideal for long-term retirement planning.
- Traditional savings accounts provide high liquidity and FDIC insurance but often fail to outpace inflation.
- Tax deferral in annuities allows for faster compounding compared to the annual taxation of savings accounts.
- Early withdrawals from annuities may incur surrender charges and IRS penalties, so liquidity is limited.
- A balanced approach using both annuities and savings can optimize both security and accessibility.
- American Gulf has over 50 years of expertise in financial services, founded in 1970.
- Our team provides personalized guidance to help you choose the right financial products for your needs.
Frequently Asked Questions
What is a fixed annuity?
A fixed annuity is a contract with an insurance company that guarantees a specific interest rate for a set period, providing predictable growth for retirement savings.
Are fixed annuities FDIC insured?
No, fixed annuities are not FDIC insured. They are backed by the claims-paying ability of the insurance company, such as Gulf Guaranty Life Insurance Company.
Can I withdraw money from a fixed annuity early?
Yes, but early withdrawals may be subject to surrender charges and a 10% IRS penalty if taken before age 59½.
How do fixed annuities compare to CDs?
Fixed annuities often offer higher interest rates than CDs and provide tax-deferred growth, whereas CDs offer FDIC insurance and greater liquidity.
Who is American Gulf?
American Gulf is a financial services company founded in 1970, specializing in fixed annuities and retirement solutions, with a focus on integrity and stability.
Do I need to pay taxes on annuity interest?
Interest earned in a fixed annuity is tax-deferred, meaning you do not pay taxes until you withdraw the funds. Withdrawals are then taxed as ordinary income.
How can I get started with an annuity?
You can contact our team at American Gulf to discuss your financial goals and explore our fixed annuity options. We offer personalized guidance to help you get started.
Contact Us
Ready to secure your financial future? Contact American Gulf today to learn more about our fixed annuity products and how they can fit into your retirement plan. Our team of experts is here to provide personalized guidance and answer any questions you may have. Visit our contact page or call us at (844) USA-GULF. Let us help you sail toward a prosperous future with confidence and clarity.