
FDIC-insured Certificates of Deposit (CDs) offer safety but often lag behind inflation, making them a suboptimal primary vehicle for long-term IRA growth. While they protect principal, they rarely provide the compounding power needed for a robust retirement. Investors should view CDs as a defensive component, not the sole strategy, within a diversified portfolio. To discuss how an annuity might fit your plan, contact our team.
The Safety Trap: Why Principal Protection Is Not Enough
Many investors assume that because a CD is FDIC-insured, it is the "best" choice for an IRA. This is a misconception. FDIC insurance is a guarantee of principal repayment up to specific limits, not a guarantee of purchasing power. In an inflationary environment, a CD yielding 4% while inflation runs at 5% results in a real loss of wealth. The safety of the principal does not equate to the growth of the portfolio. Our leadership team is committed to providing top-quality services to help you navigate these complexities.
For an IRA, which is designed for long-term accumulation, the opportunity cost of locking funds into a low-yield CD is significant. You are trading potential growth for certainty. While certainty is valuable, it is only one dimension of a successful retirement plan. A balanced approach requires assets that can outpace inflation over decades.
Maximizing the Tax-Deferred Advantage
One of the primary benefits of an IRA is tax-deferred growth. However, the type of asset inside the account matters. Tax-deferred growth is most powerful when applied to assets with higher potential returns, such as equities or diversified funds. Placing high-yield, tax-advantaged money into a low-yield CD wastes the tax shelter. The tax benefit is a multiplier; it multiplies whatever return the asset generates. If the return is low, the benefit is small.
Liquidity Constraints and Surrender Charges
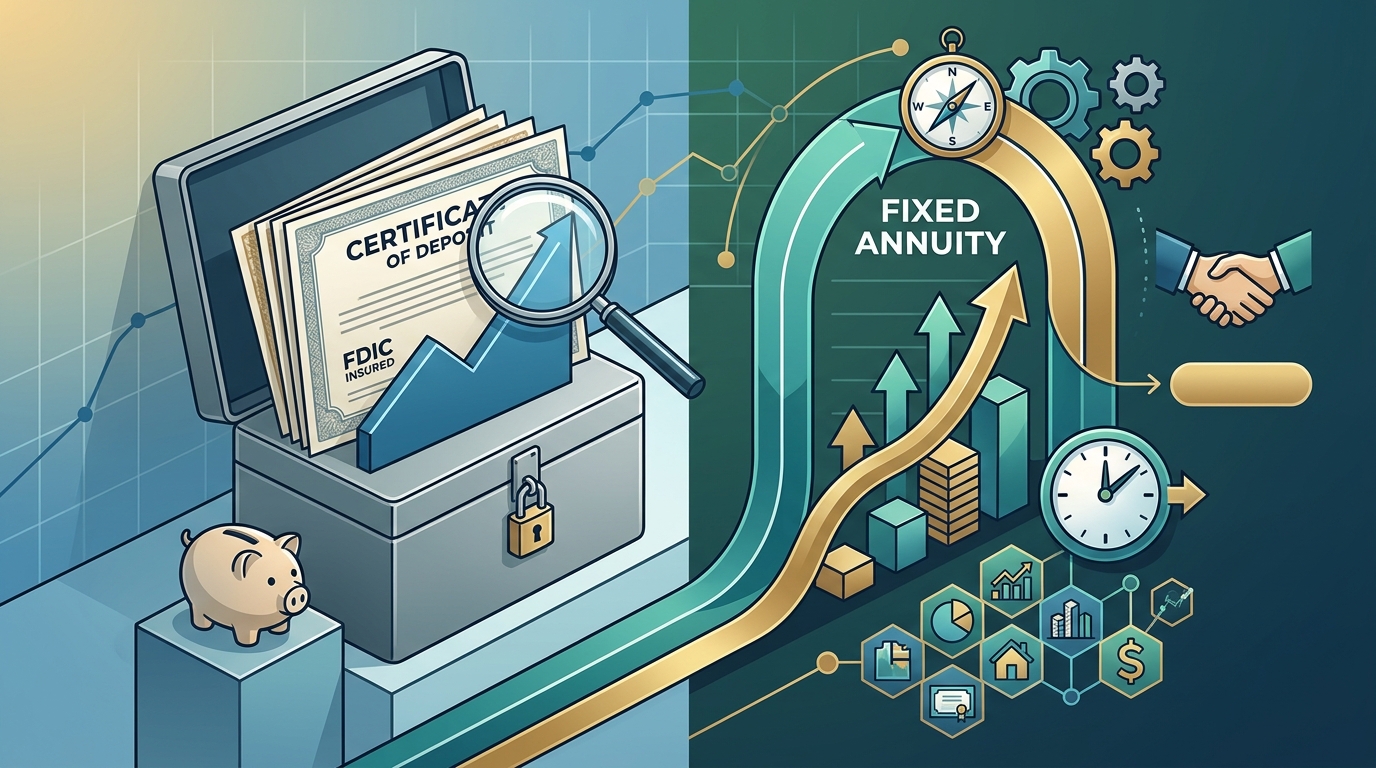
CDs are illiquid by design. To earn the higher interest rates associated with longer terms, you must lock your money away for a set period. A CD is a time-bound financial instrument that penalizes early withdrawal through interest forfeiture or surrender charges. In a retirement account, this lack of flexibility can be problematic. If you need to access funds for a medical emergency or a family crisis, you may face penalties that erode your savings.
Furthermore, if you are using a CD inside an IRA, the surrender charges are paid from your pre-tax or post-tax retirement funds. This reduces the amount available for future growth. While some IRAs allow for penalty-free withdrawals under specific conditions, the structural nature of CDs still limits your ability to pivot your strategy quickly. This rigidity is a significant drawback compared to more liquid investment options.
The Role of CDs in a Diversified Portfolio
While CDs may not be the "best