
Fixed Annuities for Retirement Income Planning: The Ultimate Guide
Fixed annuities provide a reliable, tax-deferred foundation for retirement income by guaranteeing a steady growth rate and protecting your principal from market volatility. This guide explains how to use these contracts to build a secure financial safety net. We will cover tax deferral strategies, annuity laddering, guaranteed income floors, longevity protection, and payout options to help you plan with confidence. according to Annuities A brief
Tax Deferral and Growth
Tax deferral is a core feature of fixed annuities that allows your savings to grow without immediate tax liability. Unlike taxable investments where you pay taxes on interest or dividends every year, annuity earnings remain untouched until withdrawal. This compounding effect can significantly increase your total retirement assets over time.
How Tax-Deferred Growth Works
A fixed annuity is an insurance contract that guarantees a specific interest rate for a set period. Because the growth is tax-deferred, the full amount of your principal plus accrued interest continues to compound. This is particularly beneficial for individuals in higher tax brackets who want to defer tax payments until they are in a lower bracket during retirement.
Qualified vs. Non-Qualified Accounts
You can hold a fixed annuity in a non-qualified account or inside a tax-qualified plan like an IRA. While annuities inside tax-qualified plans do not provide additional tax benefits, they remain subject to Required Minimum Distributions (RMDs). For non-qualified annuities, a portion of your withdrawal is considered a return of premium and is not taxed, while the rest is taxed as ordinary income.
Understanding these tax implications is crucial for optimizing your retirement portfolio. Explore our Insurance 101 guide to learn more about these fundamental concepts and how they apply to your specific situation. according to Annuities A brief
Annuity Laddering Strategies
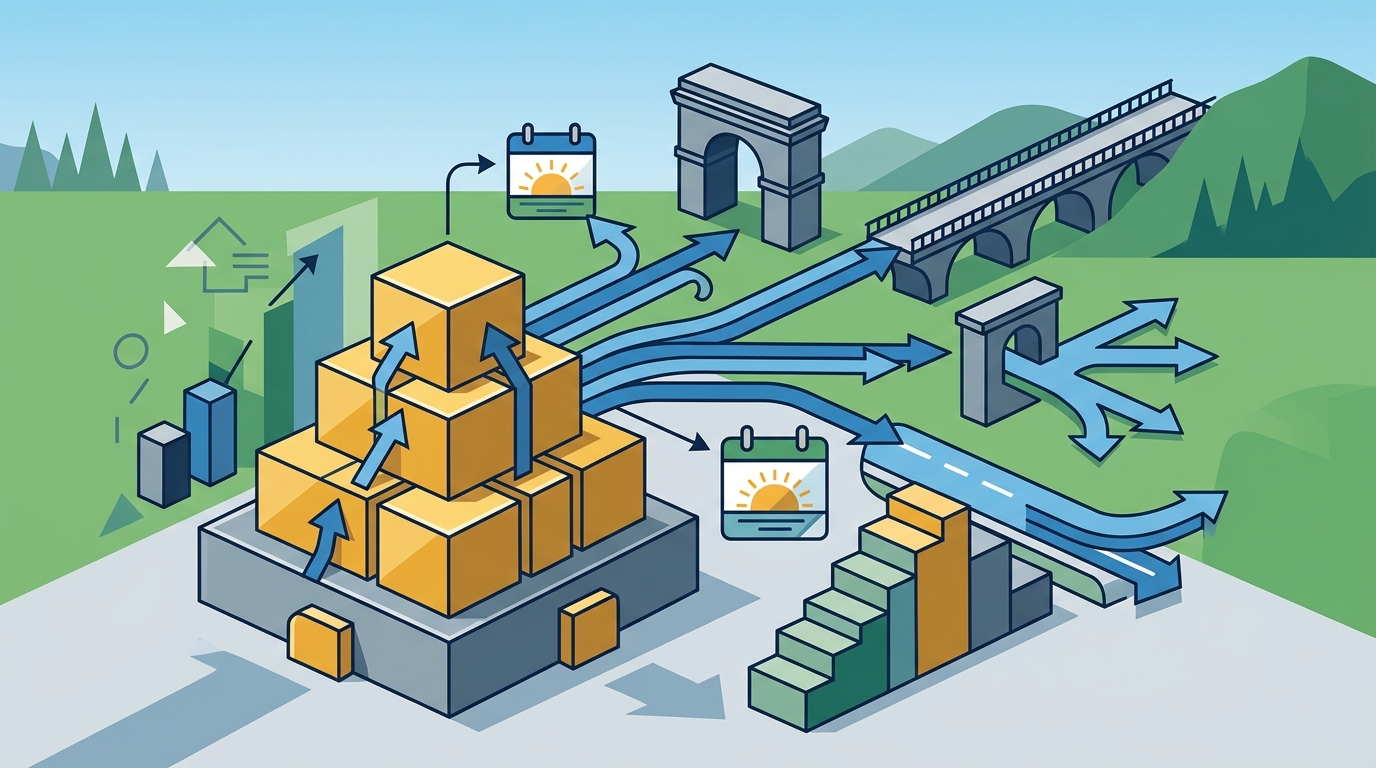
Annuity laddering is a strategy where you purchase multiple fixed annuities with different maturity dates to create a staggered stream of income. This approach helps manage interest rate risk and provides liquidity at various points in your retirement timeline.
Building the Ladder
By spreading your investments across contracts with 5, 6, and 7-year terms, you ensure that a portion of your capital becomes accessible or convertible to income at regular intervals. This prevents you from locking all your funds into a single long-term contract, which could limit your flexibility if your needs change.
Benefits of Staggered Maturities
Laddering allows you to take advantage of potentially higher interest rates in the future. If rates rise, you can reinvest maturing funds into new contracts with better yields. This strategy balances the security of guaranteed rates with the opportunity to capture market improvements.
At American Gulf, we offer Multi-Year Guaranteed Annuities (MYGA) with terms of 5, 6, and 7 years. These products are designed to help you build a stable, long-term income strategy with confidence.
The Guaranteed Income Floor
A guaranteed income floor is a baseline level of retirement income that is secured regardless of market performance. Fixed annuities provide this floor by guaranteeing a minimum interest rate or a specific payout amount upon annuitization.
Protection Against Market Volatility
Since fixed annuities are not tied to market fluctuations, your principal is protected from downturns. This stability is essential for covering essential living expenses such as housing, utilities, and healthcare. Knowing that a certain amount of income is guaranteed allows you to invest the rest of your portfolio in higher-growth assets with less anxiety.
Stability for Essential Expenses
By allocating a portion of your retirement savings to a fixed annuity, you create a predictable cash flow. This reduces the risk of outliving your assets, a common concern among retirees. The guaranteed nature of these payments provides peace of mind, knowing that your basic needs are covered no matter what happens in the financial markets.
Longevity Protection
Longevity protection is the ability of an annuity to provide income for as long as you live, mitigating the risk of outliving your savings. This feature is particularly important for individuals who have a family history of long life or who have significant assets to preserve.
Life Annuity Options
When you annuitize a fixed annuity, you can choose a payout option that continues for your lifetime. This ensures that you receive a steady stream of income until your passing. If you have a spouse, you can also select a joint-and-survivor option, which provides income to your spouse for their lifetime as well.
Legacy Planning
Some payout options allow for a death benefit, ensuring that any remaining value is passed to your beneficiaries. This combines the security of lifetime income with the ability to leave a financial legacy for your loved ones. It is a comprehensive solution for those who want to protect both their own future and that of their family.
For more information on how annuities can support your legacy planning goals, visit our products page to see the full range of solutions available.
Payout Options and Settlement
Payout options, also known as settlement options, determine how and when you receive the income from your annuity. Choosing the right option is critical to aligning your annuity with your overall retirement income plan.
Common Settlement Options
| Option Type | Description | Best For |
|---|---|---|
| Lump Sum | Receive the entire contract value at once. | Immediate liquidity needs or large expenses. |
| Fixed Term | Receive payments for a specific number of years. | Covering expenses during a specific life stage. |
| Life Annuity | Receive payments for the life of the annuitant. | Longevity protection and essential living costs. |
| Joint and Survivor | Receive payments for the lives of two annuitants. | Couples who want to ensure income for both. |
Considerations for Choosing
When selecting a payout option, consider your other sources of income, such as Social Security or pensions. You may choose a shorter term to supplement other income or a life annuity to cover essential expenses. It is important to review your contract terms carefully, as some options may have different tax implications or surrender charges.
Consult with a licensed insurance agent to help you select the payout option that best fits your financial goals. Our team at American Gulf is ready to guide you through this process.
Key Takeaways
- Fixed annuities offer tax-deferred growth, allowing your savings to compound without annual tax liability. according to Big Bang Tax
- Annuity laddering with 5, 6, and 7-year terms provides flexibility and helps manage interest rate risk.
- A guaranteed income floor protects your essential expenses from market volatility.
- Longevity protection ensures you do not outlive your savings by providing lifetime income.
- Payout options can be tailored to your specific needs, from lump sums to life annuities.
- Fixed annuities are a low-risk component of a diversified retirement portfolio.
- Consulting with a licensed agent is essential for selecting the right contract and payout option.
Frequently Asked Questions
What is a fixed annuity?
A fixed annuity is an insurance contract that provides a guaranteed interest rate for a specific period, offering a secure and low-risk way to grow tax-deferred money for retirement.
How does tax deferral work in an annuity?
Tax deferral means you do not pay taxes on the interest earned while it is in the annuity. You only pay taxes when you withdraw the money, which can be advantageous if you are in a lower tax bracket during retirement.
What is annuity laddering?
Annuity laddering is a strategy where you purchase multiple annuities with different maturity dates to create a staggered stream of income and manage interest rate risk.
Can I get lifetime income from a fixed annuity?
Yes, you can choose a life annuity payout option, which provides guaranteed monthly payments for the rest of your life, protecting you from outliving your savings.
What are the risks of fixed annuities?
The primary risks include inflation, which can erode the purchasing power of your fixed payments, and liquidity constraints, as early withdrawals may be subject to surrender charges.
How do I choose the right payout option?
Consider your other income sources, essential expenses, and longevity goals. A life annuity is best for essential expenses, while a fixed term may be better for supplementing other income.
Conclusion
Fixed annuities are a powerful tool for retirement income planning, offering tax-deferred growth, guaranteed income, and longevity protection. By understanding how to use these contracts, you can build a secure financial foundation for your retirement. Contact American Gulf today to discuss how our fixed annuities can fit into your retirement plan.